
In 1784 Charles-Joseph Mathon de la Cour, a writer in Lyon, in France, published a made-up will. Its title played on the French name of one of Benjamin Franklin’s own books, and it was supposed to be the will of an old arithmetic teacher who left 500 livres, the French money of the day, to grow at 5% a year. It set out what the money should do after a hundred years, two hundred, and on to five hundred, each plan more ambitious than the last, because the pile kept growing faster.
Franklin, then living in Paris, was sent four copies. He sent one on to a friend in London, writing that it showed “strongly and pleasantly” the “immense Powers of compound Interest”. Then he did it for real. In 1789, a year before he died, he added a codicil, a late addition, to his own will. It left £1,000 to his birthplace, Boston, and £1,000 to Philadelphia, where he had made his fortune. Each city was to lend the money at 5% a year to young married tradesmen under 25 who had served an apprenticeship there, years of training under a master, in loans of £15 to £60, each paid back a tenth at a time, and lend it on again as it came back.
Franklin did the sums himself. After a hundred years, he wrote, each fund would be £131,000. The city should spend £100,000 of it on public works and lend out the other £31,000 for another century, by the end of which it would be £4,061,000. His arithmetic was right: £1,000 at 5% a year for a hundred years is £131,501. And he knew what could spoil it. “I have, perhaps, too much flattered myself with a vain Fancy,” he wrote, that the plan would run that long without interruption.
It didn’t. Fewer young tradesmen came to borrow than he had hoped, at least in Philadelphia. In Philadelphia the board that ran the fund from 1869 made only ten loans in its first five years, and in 1874 asked a court to raise the age limit to 35 so that more would borrow. Still, the thousand pounds did something. After the first hundred years, Boston’s money helped pay for a technical school, which took its first students in 1908, and most of Philadelphia’s public share went to the Franklin Institute, whose science museum is still open. When the two centuries ended in 1990, Boston’s share stood at about $4.5 million. Philadelphia’s was smaller, and accounts of it differ.
Franklin’s plan was a bet on one idea: that money which earns interest, and then earns interest on its interest, grows in a way people don’t expect.
Interest that earns interest
Lend someone Rs. 10,000 at 10% a year (a round rate, chosen to keep the sums easy; real rates are in the box at the end) and there are two ways the interest can be counted.
In the first, the interest is worked out on the Rs. 10,000 every year, and only on that. Each year adds Rs. 1,000. After one year the lender is owed Rs. 11,000, after two Rs. 12,000, after thirty Rs. 40,000. This is simple interest (साधारण ब्याज). It grows by the same step every year, so drawn on a graph it is a straight line. The sum is the one every Grade 8 student learns: interest is the amount lent, times the rate, times the years.
In the second, each year’s interest is added to the sum, and next year’s interest is worked out on the bigger sum. After one year it is Rs. 11,000, the same as before. But in the second year the 10% is taken of Rs. 11,000, so it adds Rs. 1,100, not Rs. 1,000, and the total is Rs. 12,100. In the third year 10% of Rs. 12,100 adds Rs. 1,210. This is compound interest (चक्रीय ब्याज, or चक्रवर्ती ब्याज in the finance course), interest on interest. At first the two ways hardly differ: after three years it is Rs. 13,310 against Rs. 13,000. Then they part. After ten years compound interest has made Rs. 25,937 against Rs. 20,000. After thirty it has made Rs. 1,74,494, against simple interest’s Rs. 40,000.
Each year the sum is multiplied by the same 1.10, so after n years the Rs. 10,000 has been multiplied by 1.10 n times:
where r is the rate for one year (0.10 for 10%). That is all compounding is. Grade 10 Math, Unit 2 works the sums through, and Grade 8 Math, Unit 7 the simple ones.
The line bends because each year adds a share of a bigger and bigger sum. Simple interest adds the same Rs. 1,000 forever. Compound interest added Rs. 1,000 in the first year, Rs. 2,358 in the tenth, and Rs. 15,863 in the thirtieth, all at the same 10%. Nothing about the rate changed. The only thing that grew was the pile it was taken from.
This has an odd effect on which rupees matter most. A rupee saved early isn’t worth more than a rupee saved late because it is a better rupee, but because it has more years to be multiplied. At 5% a year, Rs. 10,000 put away at 15 and left alone until 60 becomes about Rs. 89,850. The same Rs. 10,000 put away at 25 becomes Rs. 55,160. Ten years of waiting at the start cost more than a third of the end, and those ten years are not the last ten but the first, when the pile was smallest and seemed to be doing nothing.
The picture below makes the same point with a saving made every month. The dashed line starts five years later and ends on the same day.
At Rs. 500 a month for 20 years at 5%, Sabina, who is made up, puts in Rs. 1.2 lakh, and interest takes it to about Rs. 2.06 lakh. Starting five years later, she puts in Rs. 30,000 less and ends about Rs. 72,000 short. Stretch it to 30 years and the interest outgrows everything she put in herself. Morgan Housel, an American who writes about money, calls the first rule of compounding “Never interrupt it unnecessarily.” Taking out the interest each year turns compound interest back into simple interest, and the line goes straight again.
How often interest is added makes a difference too, smaller but real. Say a bank quotes 12% a year, another round rate, and adds it all once, at the year’s end: Rs. 100 becomes Rs. 112. Now say it adds half of that, 6%, every six months, which is called half-yearly or semi-annual compounding. After six months Rs. 100 is Rs. 106, and the second 6% is taken of Rs. 106, so the year ends at Rs. 112.36. Added every three months, 3% at a time, it ends at Rs. 112.55. Added every month, 1% at a time, at Rs. 112.68. The 12% the bank quotes is called the nominal rate. What the money really grows by in a year, 12.36% or 12.68% depending on how often interest is added, is the effective rate. Two accounts with the same quoted rate can pay different amounts, and the one that adds interest more often pays more. Every time interest is added, the interest already added starts earning too. Borrowing works the same way from the other side, which is why a loan’s monthly rate needs care, and Chapter 14 comes to it.
Doubling time
There is a shortcut for compound interest that is more than five hundred years old. Divide 72 by the rate, and the answer is about the number of years money takes to double. At 6% a year, 72 ÷ 6 = 12 years. At 9%, eight. At 3%, twenty-four.
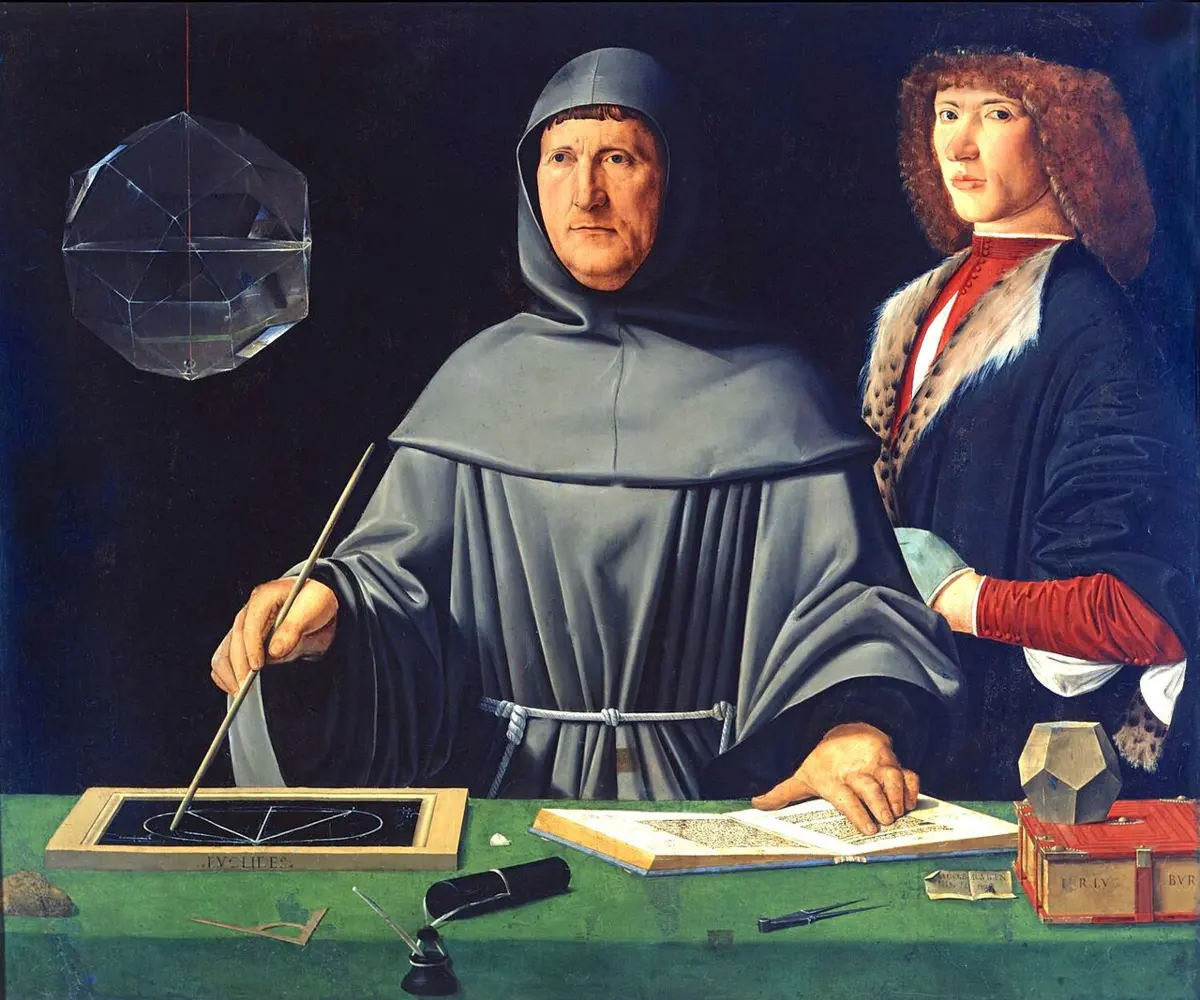
The oldest statement of it anyone has found was printed in 1494 by Luca Pacioli, an Italian friar and teacher of mathematics, in his Summa, a book of arithmetic and geometry. Hold 72 in your mind, he told his readers, and divide it by the interest. He gave the 6% example himself, and no reason, so the rule may be older still. Later arithmeticians puzzled over where the 72 came from. It is not exact. At 6% the true answer is 11.9 years, and at 24% it is 3.2 rather than 3. But it is close for the rates people meet in ordinary life, closest at around 8%, and 72 divides easily by 2, 3, 4, 6, 8, 9 and 12, which is the whole of its charm.
The rule also works backward, which answers the two questions Nepal’s finance course asks students to solve: how long, and at what rate. To double money in ten years, it needs to grow by about 72 ÷ 10, a little over 7% a year (the exact answer is 7.18%). The same can be done for any growth, not only doubling. To turn Rs. 1 lakh into Rs. 1.5 lakh in six years needs about 7% a year, because 1.07 multiplied by itself six times is 1.5, and the sum can be tried rate by rate until it fits. It also shows where Franklin’s £131,000 came from. At 5% money doubles every 14 years or so, and a hundred years holds about seven such doublings: 2 × 2 × 2 × 2 × 2 × 2 × 2 is 128. That is how a sum can become more than a hundred times bigger without any one year looking special.
Prices double the same way. In every year since 2016/17, prices in Nepal have risen by between 3% and 8%. If they rise 6% a year, what costs Rs. 100 today would cost about Rs. 200 in twelve years, when a student reading this is in their mid-twenties.
Running it backward
Compounding answers one question: what will a sum be later? It has a twin that answers the opposite one: what is a later sum worth now? Behind both is the idea finance calls the time value of money: a rupee today is worth more than a rupee later, because today’s rupee can be lent out and grow. The answer is the sum that, put away today, would grow into the later one, and over many years it shrinks a lot. Rs. 1 lakh promised in ten years is worth about Rs. 61,400 today at 5%. Promised in twenty years, about Rs. 37,700. Going forward is compounding (चक्रवर्तीकरण), going back is discounting (बट्टाकरण), and the backward sum is the forward one turned over:
What it is worth today is called its present value, and what it will grow into, its future value. Finance treats every sum of money this way, as something that happens at a time: a cash flow. Money that comes in is an inflow, money that goes out an outflow. Some cash flows are a single sum, like Franklin’s £1,000. Some are a row of equal sums at equal steps, an annuity, like Sabina’s monthly saving above. Some go on forever, which comes next. And some are uneven, different sums at different times, which is what most real life looks like.
To compare uneven sums, they have to be brought to one date, because a rupee in one year and a rupee in three years are not the same thing and can’t simply be added. People who work with money draw them on a time line: today at the left, the years along it, arrows up for money in and down for money out.
Take a decision Sabina might face at 19. A computer course costs Rs. 40,000, paid now. She thinks, without being sure, that it will raise her pay by Rs. 10,000 in the first year after it, Rs. 15,000 in the second and Rs. 20,000 in the third. Added up, that is Rs. 45,000 for Rs. 40,000, which looks like a gain. But the Rs. 20,000 comes three years from now. Brought back to today at 5%, the three sums are worth Rs. 9,524, Rs. 13,605 and Rs. 17,277, and together Rs. 40,406. The course pays for itself, but only just.
The same sums can also be carried forward instead, all to the end of year three. The Rs. 10,000 then earns two years’ interest and becomes Rs. 11,025, the Rs. 15,000 earns one year’s and becomes Rs. 15,750, and the last Rs. 20,000 stays as it is: Rs. 46,775 in all. The fee, had it stayed in the bank, would have grown to Rs. 46,305 by then. It is the same comparison seen from the other end, and it gives the same answer, because it is the same arithmetic.
The sum depends on the rate. At 10% the three sums are worth only Rs. 36,514 today, less than the fee, and the course no longer pays. And it depends far more on the guesses: whether the raise comes at all, how long it lasts, whether the course leads somewhere else entirely, which the numbers can’t see. What the sum does is make the question exact. It turns “is it worth it?” into “do I believe the course will bring more than Rs. 40,406 of today’s money?”, which is something a person can think about. A business asks the same question of a new machine, which Accounting, for the Curious takes up in Chapter 25.
Forever
On 27 November 1895 Alfred Nobel signed a will that left most of his fortune to “constitute a fund, the interest on which is to be distributed annually as prizes”. The money was never to be spent, only its earnings, so the prizes could go on for as long as the fund lasted. The fund began with more than 31 million Swedish kronor.
A row of equal payments that never ends is called a perpetuity, and its present value has the simplest formula in finance. If a fund earns 5% a year and pays out exactly that 5%, it never shrinks and never grows, and it can pay the same sum every year for ever. So to pay a prize of Rs. 1 lakh a year forever at 5%, a fund needs Rs. 1 lakh ÷ 0.05, which is Rs. 20 lakh:
Any fund that spends only its earnings, a scholarship fund among them, works the same way. It sounds as though an endless row of payments ought to be worth an endless amount, but discounting shrinks each later payment a little more, until payments a century away are worth almost nothing today, and the whole endless row adds up to a finite sum.
Nobel’s prize shows what the formula leaves out. The first prizes, in 1901, were 150,782 kronor each. By 1919 and 1920 they were still about 133,000 kronor, but prices in Sweden had roughly tripled in the meantime, and the prize could buy only 28% of what the first one had bought. The fund was still there, and so were the prizes. What it paid had shrunk where it counted.
What savings really gain
Which leaves one question: does interest keep up with prices? A deposit’s rate says how many more rupees there will be. Prices say how much each rupee will buy. What the saver really gains is the difference, called the real interest rate, and roughly it is the interest rate minus the rise in prices.
In mid-October 2026 Nepal’s commercial banks were paying, on average, 4.74% a year on fixed deposits and 2.81% on savings accounts. The bank keeps back 6% of the interest as tax (Chapter 5), which leaves a saver about 4.46% and 2.64%. Prices were 6.37% higher than a year before. Set those side by side. At that rate Rs. 10,000 in a fixed deposit grows in a year to about Rs. 10,446, but if prices keep rising as they had, things that cost Rs. 10,000 will cost Rs. 10,637. The saver ends the year with more rupees that buy less, about 1.8% less, and in a savings account about 3.5% less. The real rate was below zero.
A year earlier the two had stood the other way round. In mid-October 2025 fixed deposits paid 5.49% and prices had risen only 1.47% in a year, which left about 3.6% after tax and prices. Interest rates fell after that, and prices sped up. Neither is fixed, and they don’t move together.
Then why keep money in a bank in a year when it loses? Because the question is never the bank against nothing. It is the bank against the other places money can sit. Cash kept at home over the year to mid-October 2026 lost about 6% of what it could buy: Rs. 10,000 under the mattress bought what about Rs. 9,400 had bought a year before, and it could be stolen, burned or eaten by rats besides. A savings account lost less than that and stayed ready to use on any day. Money for next month’s fees, or for a surprise, isn’t meant to grow. It is meant to be there, and to lose as little as possible on the way, and a year of below-zero real interest doesn’t change that. Money meant for many years is a different matter. Over long stretches, a real rate a few points below zero is the difference between a pile that keeps its worth and one that halves, and Part 7 of this book is about the riskier things people turn to for that, and what they risk.
The plain thing to take from this chapter is that interest which earns interest grows by a share of a growing pile, so its line bends upward, slowly at first and then fast. That is why the earliest rupees do the most, and why interrupting compounding costs more than it seems. Divide 72 by the rate to find roughly how many years money takes to double. Interest added more often grows a little faster, so the rate a bank quotes and the rate a saver really gets can differ. The same arithmetic runs backward: a sum promised later is worth less today, by a calculation that lets uneven sums at different times be brought to one date and compared, and lets even an endless row of payments be given a price. And what savings really gain is the interest left after tax and after rising prices, which can be below zero in a year when a bank is still the right place for the money.
Try this
- Take the fixed deposit rate from the box below and divide 72 by it. How many years would money in a fixed deposit take to double? Then do the same with the price rise: how long would prices take to double?
- Work out the real rate on a fixed deposit today: take 6% off the deposit rate for tax, then take away the price rise. Is it above or below zero?
- Ask at a bank, or read an account’s terms, how often it adds interest to a savings account: every month, every three months, or once a year.
- Think of something you might pay for now that should pay you back later: a course, a tool, a bicycle for a job. Write the cost today and your best guess of what it brings each year, and bring each year back to today at the deposit rate.
Found a mistake? Please tell us.