
In Homer’s Odyssey, the hero Odysseus has to sail past the Sirens, whose singing draws sailors onto the rocks. He wants to hear the song and live. So he softens wax in his hands, stops his crew’s ears with it, and has them tie him upright to the mast. Then he gives one more order. If he begs to be set free, they are to tie him tighter. When the singing comes, he begs. Two of the crew bind him with stronger ropes, and the ship rows on until the voices fade.
In 2003 three economists, Nava Ashraf, Dean Karlan and Wesley Yin, tried something like it with money. Working with a small rural bank on Mindanao, an island in the south of the Philippines, they offered some of its customers a new account. It paid exactly the same interest as an ordinary savings account, 4% a year. Its only difference was a rule against the customer: money put in couldn’t be taken out until a date the customer chose, or until it reached an amount the customer chose. Most of those who opened one also took a small locked box for coins at home, like a खुत्रुके (khutruke), the clay money pot, except that the bank kept the key.
Of 710 customers offered the account, 202 opened one. A year later, the researchers compared everyone who had been offered it, whether they had opened one or not, with similar customers who had been offered nothing. The savings of the offered group had grown by 411 pesos more, about 8 US dollars, an extra rise of about four-fifths of what they had saved before the offer. An account that paid nothing extra, and only took a freedom away, made people save more. The researchers called their paper “Tying Odysseus to the Mast”.
Saving first
Saving is moving money forward, from today to a later you. The way that most often works is plain. Decide the sum before the month starts, move it out of reach on the day the money arrives, and spend the rest. Saving “whatever is left” at the end of the month rarely happens, for a reason everyone knows from the inside: at the end of the month there is nothing left.
The reason isn’t that people don’t care about later. It is that later has no voice in today’s decisions. The bank’s customers were asked two questions. Would you rather have 200 pesos today or 300 in a month? And would you rather have 200 pesos in six months or 300 in seven? The wait is the same one month in both. About 27 in every 100 were more patient in the far-off question than in the near one: ready to wait the month when it lay six months ahead, but not when it started now. Planning for later, people are patient. Living in the present, they aren’t. The same person is two people, and the one with the money in her hand is the impatient one.
Women who answered that way were more likely than other women to open the locked account. It looks as if some people know this about themselves, and choose a mast. That is the whole trick of saving first: it makes the decision while the patient person is in charge, before the impatient one gets to the money.
People have built masts for a long time. In the United States in the early twentieth century, “Christmas clubs” were popular: savers signed up for a schedule of deposits and could take little out before the holiday. More recently two American economists, Shlomo Benartzi and Richard Thaler, asked workers to agree now to save part of their future pay rises, which hadn’t happened yet; giving up money that isn’t in the hand yet is easier. Among those who joined, the share of their pay saved for old age went from 3.5% to 13.6% in a little over three years.
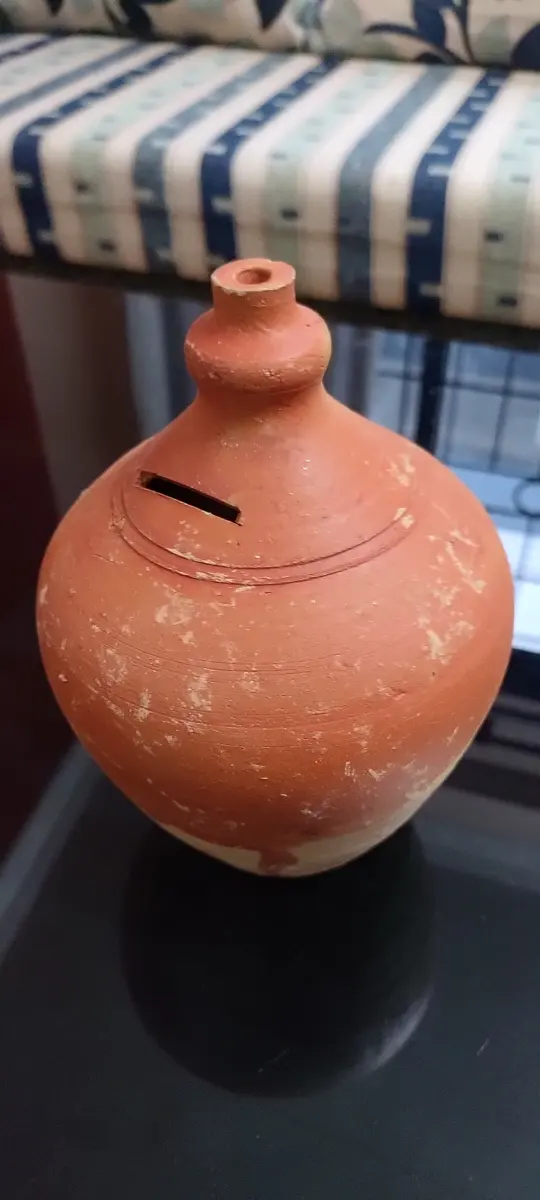
Sabina has a mast too, though she didn’t build it. Her payslip from Chapter 4 sends 11% of her basic pay to the Social Security Fund before her pay reaches her, most of it saved in her own name before she has a chance to want it. For the money she does see, she does it herself. At 19, on the day her Rs. 21,499 arrives, Rs. 2,000 goes into a separate account. Then come her needs, then whatever she likes. Nepal’s Grade 10 social studies course suggests the same habit for a class: buy a खुत्रुके together and agree that everyone puts in a fixed sum each month.
A lock has a cost, and the researchers said so. Money that can’t come out can’t come out when it’s really needed. Their account made exceptions only for a medical emergency (with the hospital’s bill), a death in the family or a move away, and the researchers wrote that they couldn’t tell from their numbers whether people were better off overall. Most customers also turned it down: 72 in every 100 offered the account didn’t open one. So the part that suits nearly everyone is the order, saving first. How firmly to lock the door is a choice each person makes about themselves.
A goal turned into a month
A big price can feel impossible and still be a plan. Sabina wants a laptop for college, Rs. 60,000, in 15 months. Divided by 15, that is Rs. 4,000 a month. If that is too much, there are only two ways to change it, and both are honest: wait longer, or choose a cheaper laptop. Seen as a monthly sum, a want also shows its price in time. A Rs. 60,000 laptop is fifteen months of putting aside Rs. 4,000.
The customers on Mindanao were asked to name a goal, and it was written on their account form. Nearly half named a celebration: Christmas, a birthday, or the yearly fiesta, when each family in the community is expected to host a large party with plenty of food. The researchers noted that families often paid for the fiesta by borrowing from local moneylenders at high interest. Saving for it turned the same party from money moved back, paid for months afterwards with interest, into money moved forward. A fifth saved for school fees, and another fifth for a business or the house. Families in Nepal have the same sort of goals, and the same choice for each of them: the festival, the school year and the roof before the monsoon can be saved for a little each month, or borrowed for all at once.
Money for surprises
Some costs can’t be planned, because nobody knows what they will be. A phone breaks, a parent falls ill, the roof leaks, a bus pass is lost, a job ends. For these a different kind of saving is needed: a small sum kept apart, used only for surprises, and filled up again first whenever it is used.
Few Nepalis lean on one. In 2024 the World Bank’s Global Findex survey asked adults in Nepal to imagine an emergency costing about a twentieth of an average year’s income per person, which comes to roughly Rs. 10,000, and to say where they would find the money within 30 days. About 52 in every 100 named family or friends. Fifteen said they would work for it, 11 would sell something, 9 would borrow, and only 10 would use savings. Forty-five in every hundred said finding it would be very difficult.
That picture says something good about Nepal before it says anything worrying. Family is the country’s oldest emergency fund, and it works: help arrives quickly, nobody charges interest, and the help goes the other way the next time. A family that turns to its relatives isn’t failing to plan. It is using the plan it has. The weakness is that the family’s money is often under the same strain at the same moment, when the harvest is poor for everyone in the village or the whole house depends on one income. And a loan taken in a hurry is the dearest kind, because the borrower has no time to ask anyone else.
The picture below is a made-up two years. Sabina has Rs. 2,000 a month to spare. Without a fund she spends it on wants each month, and when a surprise comes she borrows. With a fund she first puts the money aside until Rs. 10,000 is kept, and only then spends.
With a fund, a surprise is a dip that fills again. Without one, the same surprise becomes a loan, and the months after it belong to the lender. Nobody can be told how big a fund should be, since it depends on what a person’s life costs and how steady the income is. The same survey asked what would happen if a household lost its main income: 15 in every 100 Nepali adults said they could keep going for less than two weeks, and 37 for about a month. A month of needs is a fair first aim, and for a student, a month’s pocket money. It should be where it can be reached within a day, but not where it gets spent by accident.
Keeping it apart matters more than it seems. Money has no labels, and a rupee for surprises buys earphones as easily as any other. But people treat money differently when it sits in its own place under its own name, which the economist Richard Thaler called mental accounting. The researchers on Mindanao thought part of their account’s effect came from just this: it was money with a name, set aside for one thing. An envelope marked “surprises”, or a second account used for nothing else, does the same.
There is one more kind of saving, and it needs no reason at all. Morgan Housel, an American writer about money, calls it room for error. He quotes the investor Benjamin Graham: “The purpose of the margin of safety is to render the forecast unnecessary.” Money put by for nothing in particular is for the things nobody predicted, and those are most of the things that go wrong.
When there is little to save
All of this is harder on a small income, and that is nobody’s fault. When needs take nearly all of a month, as they do for Nepal’s poorest families, there is very little to move forward however carefully the page is planned. When the income comes by the day or the season, the fixed sum saved on payday has no payday to be saved on. And worry itself may get in the way. Four researchers tested farmers twice, before the harvest, when they were short of money, and after it, when they had been paid. The same farmer did worse on the tests before the harvest, and neither less time, poorer food, harder work nor stress explained it. Their explanation is that money worries use up the mind, leaving less for everything else. Not every study since agrees: when low-income Americans were tested, some just before payday and some just after, those short of cash did no worse on the tests, though they were more impatient about money. It is safest to say that being short of money makes careful choices harder, and leave how much harder open.
People on small incomes save all the same, in their own ways. The same survey found 20 in every 100 Nepali adults had saved at a bank or similar place in the past year, and 14 had saved in a savings club or with someone outside the family. Many also keep their savings in land and gold, which Chapter 26 takes up. And the advice from Chapter 6 for uneven income works for saving too: plan on the slow month, and save from the good one.
More than the months times the sum
Something else happens when the same sum is saved again and again. If it earns interest, the total ends up bigger than the sum times the number of times it was paid in.
Say Sabina puts Rs. 10,000 in a savings account at the end of each year for five years, and the bank adds 5% interest once a year (a rate chosen to keep the sums easy; real rates are in the box at the end). Follow each deposit to the end of the fifth year. The first one has four years to earn: Rs. 10,000 becomes 10,500, then 11,025, then 11,576, then 12,155. The second has three years, and becomes 11,576. The third becomes 11,025, the fourth 10,500, and the last, paid in on the final day, is still Rs. 10,000. Together they make Rs. 55,256. She put in Rs. 50,000, and the other Rs. 5,256 is interest, some of it interest earned on earlier interest, which is the next chapter’s subject.
A row of equal payments made at equal steps of time like this is called an annuity in finance. When each payment comes at the end of its period, as here, it is an ordinary annuity. Finance books write its total in one line, where P is each payment, r the rate for one period and n the number of payments:
For Sabina that is 10,000 × (1.05⁵ − 1) ÷ 0.05, the same Rs. 55,256.
Now suppose she pays in at the start of each year instead. Each deposit then sits in the bank one year longer than before, so each one gets one more year’s interest, and the whole total is 5% bigger, the same line multiplied by 1 + r: Rs. 58,019. Payments at the start of each period make an annuity due. There is also a deferred annuity, a row of payments that begins only after some years have passed, like a pension that starts at 60.
On a short saving the difference is small. Rs. 2,000 saved every month for a year at 5% comes to about Rs. 24,558 if paid in at the end of each month, and Rs. 24,660 at the start, about Rs. 100 more (if the bank adds a twelfth of 5% each month). It matters more over many years, and it is one more reason to save on the day the money arrives rather than at the end of the month.
The same sum can be turned round to answer a goal. To reach Rs. 60,000 in five years at that 5%, Sabina needn’t save Rs. 12,000 a year: Rs. 10,858 at each year’s end is enough, and the interest makes up the rest. Real savings accounts pay less than our made-up rate, and the bank keeps back part of the interest as tax (Chapter 5), so on a real account the gain is smaller and the sum she must save is closer to the plain division. Whether the interest even keeps up with rising prices is a question for the next chapter. The arithmetic itself comes back twice in this book. Chapter 15 runs it backward, to find the equal payments that repay a loan. Chapter 34 runs it to its end, where a lump saved over a working life is paid back month by month in old age.
The plain thing to take from this chapter is that saving works best when it comes first. The sum is decided before the month starts and moved out of reach the day the money arrives, because the person living today is always less patient than the one who planned for tomorrow. A lock, a payslip deduction or a pot whose key someone else holds can help, though a lock also keeps money from you when you need it. A goal becomes a plan when its price is divided by the months left. A small fund kept apart, used only for surprises and refilled first, stops one bad week from becoming a loan; most Nepalis turn to family instead, which works, until the whole family is short at once. Saving is harder on a small or uneven income, and that is no one’s failing. And a sum saved again and again with interest, an annuity, grows to more than the sum times the number of payments, a little more again when each payment is made at the start.
Try this
- On the day your next pocket money or pay arrives, put the sum you mean to save somewhere apart before you spend anything: a jar, a box or a separate account. Then pay for needs, then wants.
- Pick something that costs more than a month’s money. Find its price, decide by when you want it, and divide the price by the months. Write the monthly sum where you will see it.
- Find an envelope, write “Surprises” on it, and put in the first Rs. 20. Use it only for a real surprise, and fill it again first when you do.
- Take the savings rate from the box below and work out what Rs. 1,000 saved at the end of each year for three years would add up to, the same way as Sabina’s five deposits.
Found a mistake? Please tell us.