
Ask four people what Yasmin’s shop is worth and you could get four honest answers. Her bank might say: whatever the shop’s things would fetch if it closed tomorrow and sold everything, since that is what would be left to repay the loan. A buyer looking for a business might say: whatever the shop will earn over the next ten years. A neighbor might point at the busy bus stop outside and say that the spot alone is worth a fortune. And Yasmin, with her receipts in a folder, might say: what I paid for it all.
None of them is wrong. They are answering different questions. But a set of accounts can’t give a different answer to everyone who asks, and it can’t change its answer from month to month as moods and prices change. So accountants settled, long ago, which questions the books answer and how. Those settled answers are the rules behind every journal, ledger and balance sheet. In Nepali they are लेखाविधिका आधारभूत मान्यता, the basic concepts of accounting, and they are often called by an English name, generally accepted accounting principles, GAAP for short.
In plain words there are only a handful of them. The business is counted as a person of its own. Only what can be put in money is counted. The business is assumed to go on. Things are recorded at what they cost. Each year carries its own income and its own costs. When in doubt, the books lean toward caution rather than hope. And the same method is used every year. Everything else in the subject is built on those, and they are the reason two accountants given the same box of receipts will produce much the same books. Each one answers a question someone could reasonably argue about, and settles it.
What gets counted
The first rule is the line drawn round the business, apart from its owner: Yasmin’s savings put in are the shop’s capital, her phone is not the shop’s at all, and the cash she takes home for groceries is drawings, not a cost.
The second is that only what can be measured in money goes in. This is the money measurement concept, मौद्रिक मापनको मान्यता. A shop buys “some good shelves” in ordinary speech, but in the books it buys shelves for a stated number of rupees, because a page that says “good shelves, a loyal customer, a cheerful helper” can’t be added up. Money is the one measure that can turn paint, a scooter, a month’s rent and a debt from a customer into figures that can stand in one column. The price of that is everything the rupee can’t measure stays out: the helper who knows every customer by name, the trust of the hardware dealers in the bazaar, the bus stop.
Hidden inside this rule is a quieter assumption: that a rupee spent in one year is the same size as a rupee spent in another. It isn’t. By the World Bank’s figures, prices in Nepal in 2025 were about 3.7 times what they were in 2005, so a rupee of 2005 bought roughly what Rs. 3.70 buys now. Accounts mostly ignore that, and for a young shop it hardly matters. For a business that has owned a building for forty years, it matters a great deal, and the books will come back to it below.
Two more rules are so simple they are easy to miss. One is that every transaction has two sides of equal size, which is often listed as a concept in its own right, the dual aspect, द्विपक्षीय अवधारणा. The other is the accounting period, लेखा अवधिको मान्यता: the business’s life, which has no natural end, is cut into equal slices so that its owner can ask how each one went. In Nepal the slice is usually the financial year that the government keeps, from the first of साउन (Saun) to the last day of असार (Asar). Other countries cut the year at other places, and in many a company may choose its own, but almost everyone uses twelve months, so that one year can be set beside the next.
The shop will go on
Now the question Yasmin’s bank and Yasmin answered differently: what are the shop’s things worth?
Suppose that a few months after opening she buys a delivery scooter for Rs. 240,000, and a dealer would give her Rs. 170,000 for it the next day. Has the shop lost Rs. 70,000 by buying it? Only if it means to sell the scooter tomorrow. It doesn’t. It means to use it, for years, to carry tins of paint to building sites. The scooter’s worth to the shop is the deliveries it will make, and the price a dealer would pay today is beside the point.
So accounts are kept on the assumption that the business will carry on, the going concern concept, निरन्तरताको मान्यता. The international board that writes accounting standards puts it carefully: financial statements are normally prepared on the assumption that the business “will continue in operation for the foreseeable future”, with no intention or need to close down. Not forever, which nobody can know. The foreseeable future, which in practice means the managers must look at least twelve months ahead and see no reason to stop.
This one assumption is what lets most of the other rules work. Because the shop will still be there next year, the scooter can be counted at what it cost and its cost spread over the years that use it. Take the standard example: a machine bought for Rs. 500,000 that will run for five years is not a Rs. 500,000 cost of the year it was bought, but Rs. 100,000 a year for five years. Spreading a cost that way, depreciation, gets a chapter of its own later. Because the business will carry on, too, it makes sense to separate what it has from what it spends, and to keep a list of what it is owed and what it owes, debts that will only be settled in some later month.
When the assumption fails, the rule changes with it. If an owner decides to close, or the business is so deep in debt that closing is the only way out, the accounts can’t pretend otherwise. They “may have to be prepared on a different basis”, in the board’s words, and must say which. On that basis the bank’s question becomes the right one: what will each thing fetch when it is sold, and is that enough to pay everyone? A going concern is valued by what it will do. A business that is closing is valued by what it can be sold for.
What it cost
Then there is the cost concept: a thing is recorded at what was paid for it, its historical cost. If Yasmin buys shelves for Rs. 70,000, the books say Rs. 70,000, and they go on saying it, whatever shelves cost next year, less the part of the cost already used up.
It can seem a strange choice, since the price paid is the one figure certain to go out of date. But it has two great virtues. It is a fact, not an opinion: there is a bill to prove it, and anyone checking the books can find the bill and see the same number. And it is the same for everybody. Ask three people what the shelves would sell for and you get three guesses; ask what was paid and you get one answer.
The cost of the rule shows up with time. Picture a family firm that bought a plot of land in the Kathmandu Valley forty years ago. Its books still show the land at what it cost then, a tiny figure beside what the same land would sell for today, so the balance sheet makes the firm look much poorer than it is. Nobody has lied. The rule has simply been followed for a long time while prices rose.
So this is a rule that bends, and the standards say exactly how. Under the international standard for property and equipment, a business may choose to keep a whole class of its assets, all its land, say, or all its buildings, at a fresh value instead of at cost, so long as that value “can be measured reliably”, usually by a professional valuer. It must then revalue the whole class, never just the pieces that have gone up, and often enough that the figure stays close to the true value. Where prices rise so fast that money is losing its value within the year, the bending goes further. In what the standards call a hyperinflationary economy, one sign of which is prices that have about doubled over three years, a company’s figures must be restated in today’s money, because comparing amounts from different months, the standard says, is otherwise “misleading”.
Each year its own
The next question sounds simple: when did the shop earn its money?
Suppose Yasmin sells Rs. 12,000 of paint to a builder in the last week of असार, and he pays her in साउन. Was that income of the old year or the new one? There are two ways to keep accounts, and they answer differently. In cash basis accounting, नगदमा आधारित लेखा, income is written down when cash comes in and costs when cash goes out, so the paint is the new year’s income. In accrual basis accounting, प्रोदभावी लेखा, a transaction is recorded when it happens, whenever the cash moves, so the paint belongs to the year in which it was sold.
Cash basis is simpler and shows at once how much cash there is, and Nepal’s government offices, many non-profit organizations and small, simple businesses keep their accounts this way. But it can mislead badly. A shop that sold heavily on credit in its last month would look as if it had a poor year, and a shop that delayed paying all its bills would look as if it had a good one. So businesses that aim at a profit, from a hardware shop that keeps proper books to a bank, keep their accounts on the accrual basis, and international standards require it of every company that follows them, for everything but the statement of cash flows.
Three rules make the accrual basis work, and each has a name.
The first decides when income counts. Income belongs to the year in which it is earned, when the paint is handed over or the job is done, whether or not the money has arrived. This is called the realization concept, वास्तविकताको अवधारणा, or the revenue concept, आय प्राप्ति सिद्धान्त. The rule works in the other direction too. Suppose a school pays Yasmin Rs. 40,000 in advance for paint for its new classrooms, to be delivered next month. She has the cash, but she hasn’t earned it. Until the paint is delivered, the Rs. 40,000 is something she owes, a liability, because if the paint never came the school could ask for its money back.
The second decides when a cost counts: a cost belongs to the year whose income it helped to earn. The electricity used in असार is a cost of that year even if the bill is paid in साउन. Rent paid in advance for the next three months is not this year’s cost at all, but something the shop has, the right to use the room, which turns into a cost month by month as the months pass.
The third puts the two together. The profit of a year is that year’s income set against the costs of earning it, and nothing else: the matching concept, भिडान सिद्धान्त. The paint sold in असार is set against what that paint cost Yasmin, not against the stock she bought for the next festival season. It is the rule that makes a year’s profit mean something. Sorting the costs and income that cross a year’s line into the year they belong to is much of an accountant’s work at the year’s end.
Caution, and the same way every year
One of the oldest rules is a matter of temperament. Francesco di Marco Datini, a merchant of Prato in Tuscany who died in 1410, kept everything: his company’s papers, more than six hundred account books and about 150,000 letters, stayed in his house after his death, were put away on a stairway that led nowhere in the 1600s, forgotten, and found again in the late 1800s. Historians of accounting, starting with the German scholar Balduin Penndorf in 1933, report an entry of 1406 in those books that marks down some goods at less than before, “because we no longer value them as above since their price has gone down”. We haven’t seen the ledger ourselves, but if the reading is right, the habit of counting a fall in value before anything is sold is more than six hundred years old.
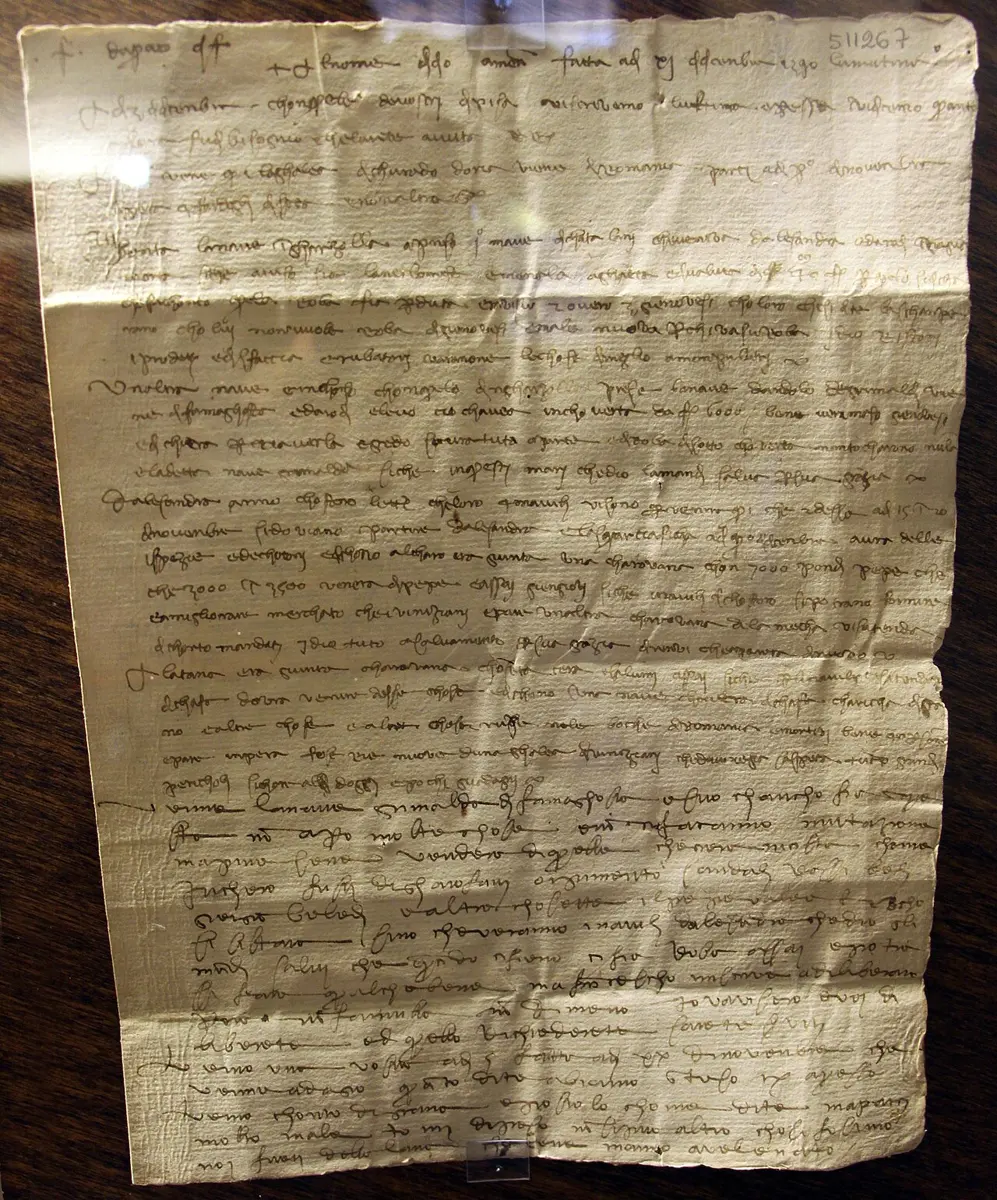
That is caution, or prudence, also called conservatism, सङ्कीर्णता. An American accounting book of 1924 put it as a slogan: anticipate all losses, but anticipate no gains. If a customer probably won’t pay, the loss is written down now. If stock has gone out of fashion and will sell for less than it cost, it is written down now. But a hoped-for rise in the value of land, or a big order that hasn’t been signed, stays out of the books until it happens. The reason is the people who rely on accounts. A lender misled into thinking a business is richer than it is can lose everything; one misled the other way only lends a little more carefully.
Caution can be overdone, and the rule-writers worry about that too. A business that hides profit in good years, by writing everything down too far, can let it reappear in bad ones and make its results look steadier than they are. For that reason the international board left the word prudence out of its framework in 2010, worried that the word could be read as working against neutral, unbiased accounts. Dropping it only caused confusion, some saying it made accounts under the standards sound imprudent, and many of those who commented on the board’s plans asked for it back. In 2018 it returned with a careful definition: “the exercise of caution when making judgements under conditions of uncertainty”. Assets and income are not to be overstated, nor liabilities and costs understated. But neither is the reverse allowed. Caution means not fooling yourself, not making yourself look poor.
The last rule is about time, and it is the reason a business’s figures can be compared across years. It is called consistency, स्थायित्व: having chosen a method, a business keeps to it. If Yasmin spreads the cost of her scooter one way this year, she does it the same way next year. Otherwise her profit could rise or fall just because she changed the arithmetic, and nobody, herself included, could tell a better year from a different method. A method may still be changed, but only for a good reason, and the international standard names the two allowed: a new standard requires it, or the new method gives “reliable and more relevant information”. Then the change must be explained, and last year’s figures restated the new way, so the two years can still be set side by side.
Beside these, accountants name two working conventions. One is materiality, सारभूतता: the rules are applied with full care to amounts that matter, and small ones are handled in the simplest sensible way. A measuring tape that costs Rs. 300 and lasts three years is, strictly, an asset, but no one will spread Rs. 300 over three years; it is simply counted as a cost the day it is bought. What counts as material isn’t a fixed number. Something is material, in the board’s words, if leaving it out or getting it wrong could reasonably be expected to influence the decisions of the people who read the accounts, and that depends on the size and kind of the business. Rs. 50,000 is a lot for Yasmin and nothing for a bank. The other is industry practice, औद्योगिक अभ्यास: some trades have settled ways of their own, and a business in that trade follows them. Two trades show it well. A builder on a long project counts its income as the work goes along, half the income when half the job is done, instead of waiting years for the end. A bank sets aside part of each year’s income against loans that are already overdue.
When a rule bends, and who says so
Put side by side, the rules pull against each other more than a list makes them sound. Cost is certain but grows stale. A fresh value is up to date but rests on someone’s estimate. Caution protects lenders but can hide a good year. Consistency makes years comparable but could keep a business stuck with an old method after a better one appears. Every rule is a trade between being checkable and being useful, and none of them is a law of nature.
So someone has to decide where each rule stops. That is what accounting standards are: written, numbered rules for each kind of thing a business might own, owe, earn or spend, which say which rule applies and when it bends. Internationally they are written by the International Accounting Standards Board, whose framework, the source of the definitions of assets and liabilities, is the reasoning behind them; it is careful to say that it is not a standard itself, and that where a standard says otherwise, the standard wins. Nepal’s Accounting Standards Board, set up in 2002, has followed the international standards closely in its own, the Nepal Financial Reporting Standards of 2013, with simpler versions for smaller businesses, and the Institute of Chartered Accountants of Nepal sees that businesses put them into practice. How the standards are made, and who must follow which, belongs to a later part of this book. Checking that they were followed is much of an auditor’s job.
For all their small print, the rules have one purpose: to make a set of accounts something a stranger can trust and compare. The international framework wants information that matters to a decision, describes faithfully what really happened, can be compared with other businesses and other years, can be checked, comes in time and can be understood. Each rule in this chapter is one way of getting there.
What this chapter leaves behind is short. The books don’t answer every question about a business; they answer a few, in agreed ways. They count only what money can measure, cut the business’s life into years, assume it will carry on, keep things at what they cost, give each year its own income and its own costs, lean toward caution and keep the same method from year to year. Each rule has a reason, each can bend, and the bending is written down by the people who write the standards, so that the books of a paint shop in Nepal and a factory in another country can be read in the same way.
Found a mistake? Please tell us.